Discounted Cash Flow (DCF) Analysis for Stock Valuation
What is Discounted Cash Flow (DCF) Analysis?
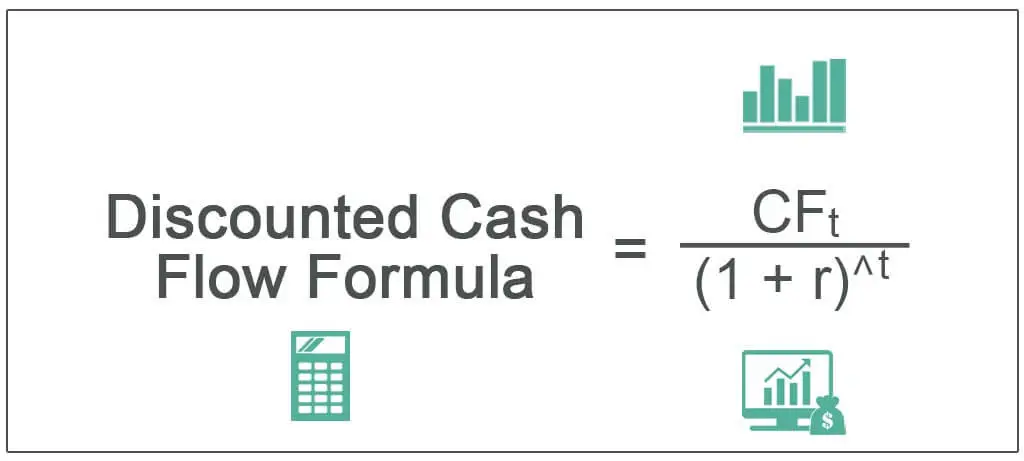
Discounted Cash Flow (DCF) analysis is a valuation method used to estimate the value of an investment based on its expected future cash flows? 🤔 It is widely used in finance and investment to determine the attractiveness of an investment opportunity. The fundamental principle behind DCF analysis is that the value of an investment is the present value of its expected future cash flows.
# Example:
# Suppose a company is expected to generate cash flows of $10 million, $15 million, and $20 million over the next three years.
# If the discount rate is 10%, the present value of these cash flows can be calculated using the DCF analysis.
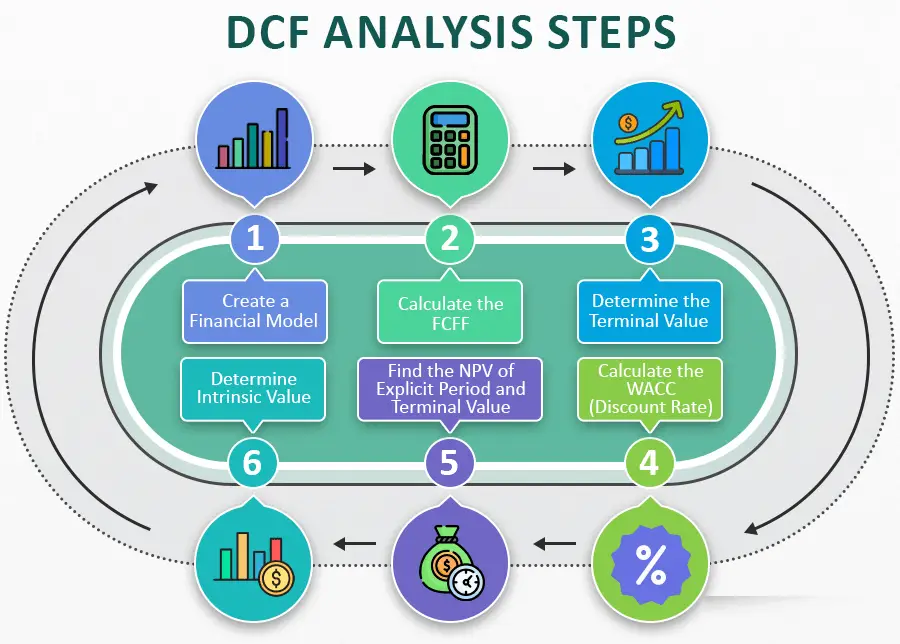
Discount Rate: The discount rate, often referred to as the cost of capital, is a crucial component of DCF analysis. It represents the rate of return required by an investor to compensate for the risk and time value of money. The discount rate is used to discount future cash flows to their present value.
# Example:
# If the discount rate is 8%, the present value of a cash flow of $100 in one year would be $92.59.
Terminal Value: In DCF analysis, the terminal value represents the value of an investment at the end of the forecast period. It is often calculated using the perpetuity growth method or exit multiple method.
# Example:
# If a company is expected to generate stable cash flows beyond the forecast period, the terminal value can be a significant portion of its total value.
How to Calculate Discounted Cash Flow (DCF): Step-by-Step
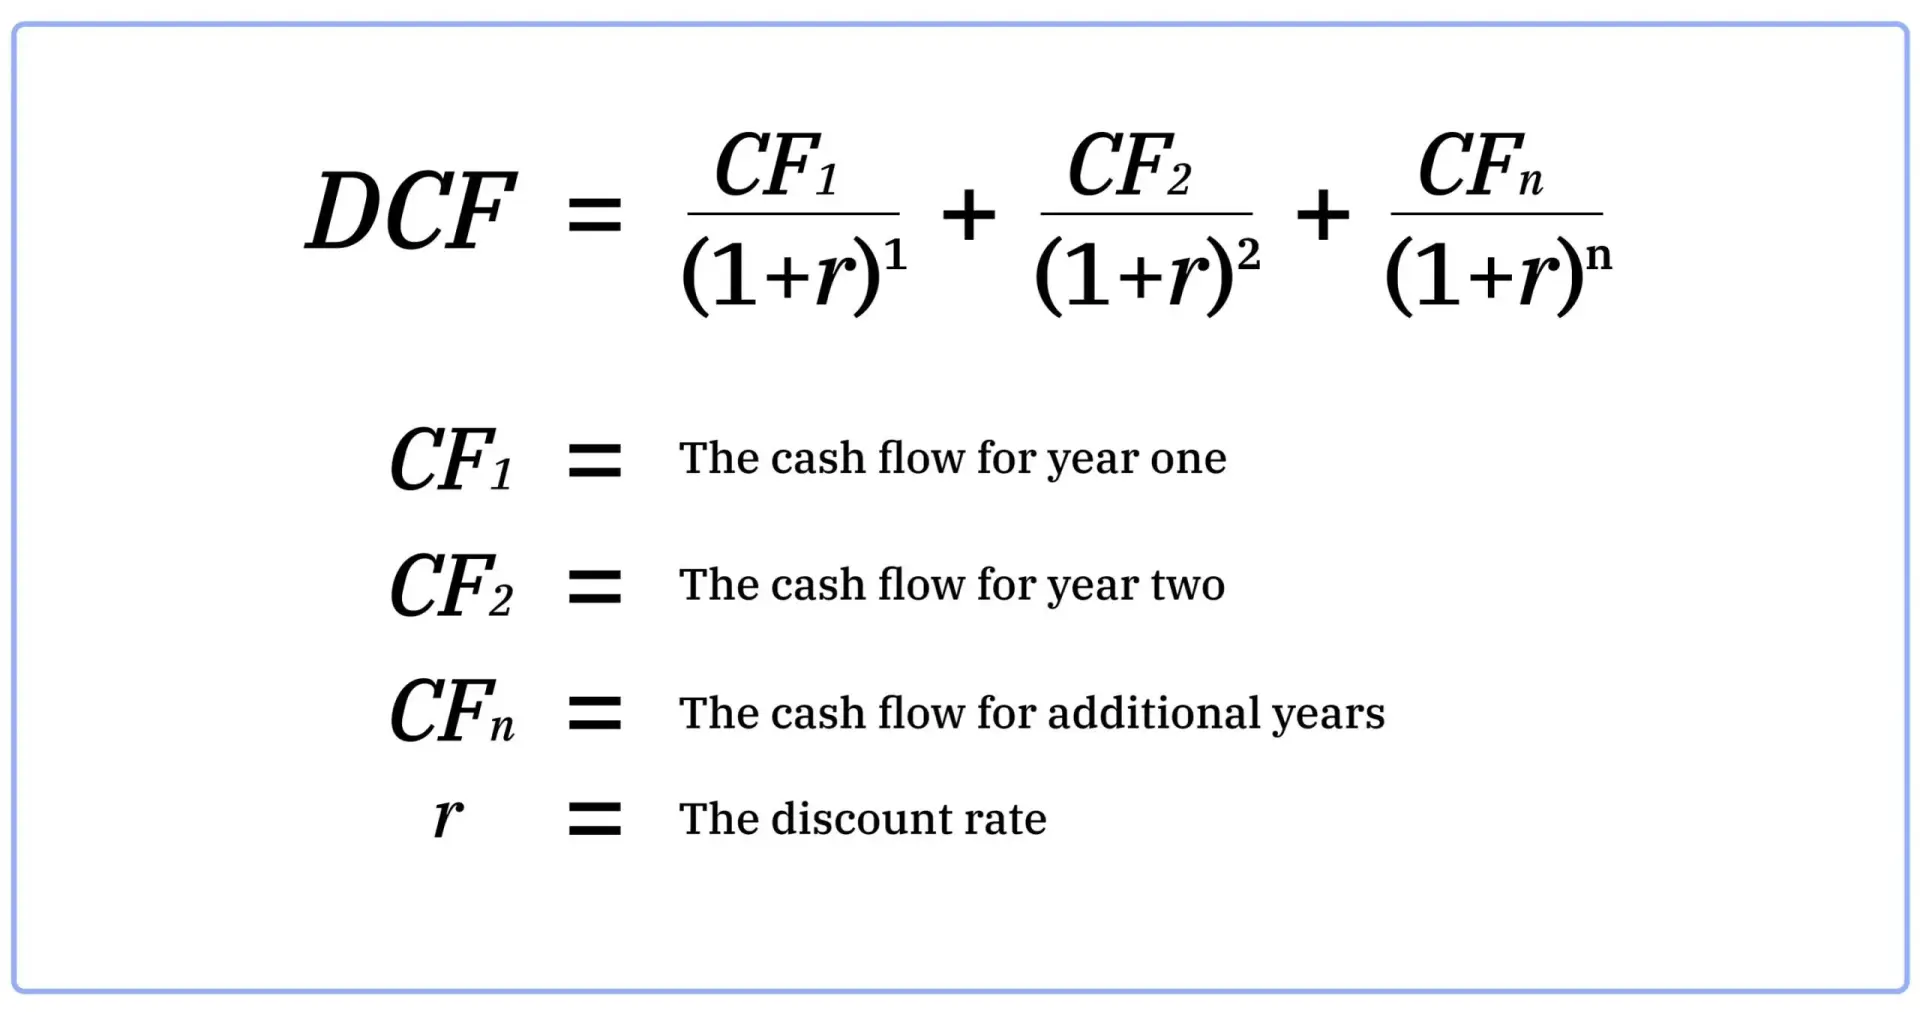
Understanding the DCF Formula
The Discounted Cash Flow (DCF) Formula is one of the most widely used methods for estimating a company’s intrinsic value. It works by converting the company’s expected future cash flows into their present value using a discount rate that reflects the time value of money and investment risk. Since money available today is worth more than the same amount received in the future, DCF analysis helps investors determine whether a stock is trading below, above, or close to its intrinsic value.
Basic DCF Formula
DCF = (CF₁ / (1 + r)¹) + (CF₂ / (1 + r)²) + ... + (CFₙ / (1 + r)ⁿ)Where:
| Symbol | Meaning |
|---|---|
| CF₁ | Cash flow expected in Year 1 |
| CF₂ | Cash flow expected in Year 2 |
| CFₙ | Cash flow expected in Year n |
| r | Discount rate or required rate of return |
This basic formula demonstrates how each year’s projected cash flow is discounted to its present value. It forms the foundation of Discounted Cash Flow analysis and explains the concept of valuing future cash flows in today’s terms.
Complete DCF Formula Used in Stock Valuation
In real-world stock valuation, analysts use Free Cash Flow (FCF) instead of general cash flow and include the Terminal Value (TV) because businesses are expected to continue generating cash flows even after the explicit forecast period.
DCF = (FCF₁ / (1 + r)¹)
+ (FCF₂ / (1 + r)²)
+ ...
+ (FCFₙ / (1 + r)ⁿ)
+ (TV / (1 + r)ⁿ)Where:
| Symbol | Meaning |
|---|---|
| FCF₁ | Free Cash Flow expected in Year 1 |
| FCF₂ | Free Cash Flow expected in Year 2 |
| FCFₙ | Free Cash Flow expected in Year n |
| r | Discount rate (typically the Weighted Average Cost of Capital or the investor’s required rate of return) |
| TV | Terminal Value representing the company’s value beyond the forecast period |
| DCF | Estimated intrinsic value of the company |
The Terminal Value often represents a significant portion of the total valuation because it captures all future cash flows expected after the forecast period. Including the Terminal Value makes this the standard DCF formula used by equity analysts, investment professionals, and institutional investors.
Example:
Suppose a company is expected to generate Free Cash Flows (FCF) of ₹10 crore, ₹12 crore, and ₹15 crore over the next three years. Assume the appropriate discount rate is 10%. Each year’s projected free cash flow is discounted back to its present value using the DCF formula. After calculating the Terminal Value, it is also discounted to its present value and added to the discounted cash flows.
The combined total represents the company’s estimated intrinsic value. Investors can then compare this intrinsic value with the current market price of the stock to determine whether it appears undervalued, fairly valued, or overvalued, helping them make more informed investment decisions.

Forecasting Cash Flows: The first step in DCF analysis is to forecast the future cash flows of the investment. This involves estimating the cash flows for a specific period, typically over a multi-year horizon.
# Example:
# A company forecasts cash flows of $5 million, $7 million, and $10 million for the next three years based on its business projections and market conditions.
Discounting Cash Flows: Once the cash flows are forecasted, they are discounted to their present value using the discount rate. This involves applying the concept of time value of money to determine the current worth of future cash flows.
# Example:
# Using a discount rate of 12%, the present value of a cash flow of $200 in two years would be $150.94.
Calculating Terminal Value: After forecasting the cash flows, the terminal value is calculated to capture the value of the investment beyond the forecast period. This involves applying the appropriate method to estimate the future value of the investment.
# Example:
# Using the perpetuity growth method, the terminal value of a company is estimated to be $150 million based on a perpetual growth rate of 3%.
Summing Present Values: Finally, the present values of the forecasted cash flows and the terminal value are summed to determine the total value of the investment.
# Example:
# The sum of the present values of forecasted cash flows and the terminal value yields the total value of the investment, which can be compared to its current market price.
DCF Analysis vs Other Stock Valuation Methods
While Discounted Cash Flow (DCF) Analysis is one of the most comprehensive valuation techniques, it is often used alongside other valuation methods to obtain a balanced view of a company’s worth. Each method has its own strengths and is suitable for different types of businesses and market conditions.
| Valuation Method | Best For | Advantages | Limitations |
|---|---|---|---|
| Discounted Cash Flow (DCF) | Intrinsic stock valuation | Based on future cash flows | Sensitive to assumptions |
| Price-to-Earnings (P/E) Ratio | Comparing similar companies | Easy to calculate | Ignores future cash flows |
| Price-to-Book (P/B) Ratio | Asset-heavy businesses | Useful for banks and financial firms | Less effective for service companies |
| EV/EBITDA | Business comparison | Considers operating performance | Does not calculate intrinsic value |
| Dividend Discount Model (DDM) | Dividend-paying companies | Suitable for stable businesses | Not useful for companies without dividends |
Experienced investors often combine DCF analysis with valuation ratios such as the P/E Ratio and P/B Ratio to verify whether a stock appears fairly valued from multiple perspectives.
Advantages and Limitations of DCF Analysis
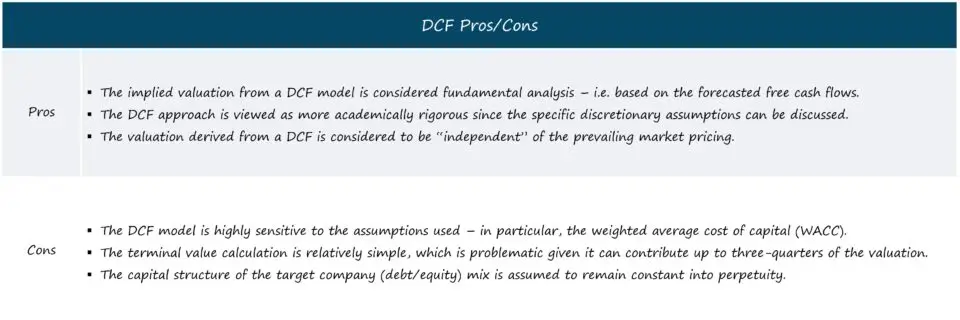
Advantages:
- DCF analysis provides a comprehensive and detailed valuation of an investment based on its cash flow potential.
- It considers the time value of money and provides a clear framework for assessing investment opportunities.
Limitations:
- DCF analysis relies heavily on the accuracy of cash flow forecasts, making it sensitive to forecasting errors.
- It requires the selection of an appropriate discount rate, which can be subjective and challenging to determine accurately.
DCF analysis is a powerful tool for stock valuation, offering a systematic approach to estimate the intrinsic value of an investment based on its expected cash flows. By understanding the components and calculation process of DCF analysis, investors can make informed decisions regarding the attractiveness of investment opportunities.
How to Choose the Right Discount Rate in DCF Analysis
One of the most important assumptions in Discounted Cash Flow (DCF) Analysis is selecting the appropriate discount rate. The discount rate reflects both the time value of money and the investment risk associated with future cash flows. Even small changes in the discount rate can significantly impact the estimated intrinsic value of a stock.
For publicly listed companies, analysts commonly use the Weighted Average Cost of Capital (WACC) as the discount rate because it represents the average cost of financing through both debt and equity. Individual investors may also use their required rate of return based on their investment objectives and risk tolerance.
Common Discount Rates Used in DCF Analysis
| Investment Type | Typical Discount Rate |
|---|---|
| Stable Blue-chip Companies | 7%-9% |
| Large Growth Companies | 8%-10% |
| Mid-cap Companies | 10%-12% |
| High-risk Businesses | 12%-15%+ |
Choosing an unrealistically low discount rate can overvalue a company, while a very high discount rate may undervalue even fundamentally strong businesses. Therefore, investors should carefully evaluate the company’s financial strength, industry risks, interest rates, and long-term growth prospects before selecting a discount rate.
Common Mistakes to Avoid in DCF Analysis
Although Discounted Cash Flow (DCF) Analysis is a powerful valuation tool, its accuracy depends on realistic assumptions. Many investors make mistakes that can lead to incorrect stock valuations.
Common Mistakes
- Using unrealistic revenue or cash flow growth assumptions.
- Selecting an inappropriate discount rate.
- Overestimating the terminal growth rate.
- Ignoring future capital expenditure requirements.
- Not considering changes in debt levels or economic conditions.
- Relying on a single DCF scenario instead of performing sensitivity analysis.
Before making any investment decision, investors should test multiple growth and discount rate assumptions to understand how sensitive the valuation is to changes in key inputs. This approach provides a more realistic estimate of a company’s intrinsic value and reduces the risk of overpaying for a stock.
These three sections add new topical coverage without overlapping your existing “DCF Calculation Process” section, while also targeting important SEO keywords like discount rate, WACC, stock valuation methods, and common DCF mistakes.
FAQs About Discounted Cash Flow (DCF) Analysis
1. What is Discounted Cash Flow (DCF) Analysis?
Discounted Cash Flow (DCF) Analysis is a valuation method used to estimate the intrinsic value of a company or investment by calculating the present value of its expected future cash flows. It helps investors determine whether a stock is undervalued, fairly valued, or overvalued.
2. What is the DCF formula?
The basic DCF formula is:
For stock valuation, analysts typically use:
Here, FCF means Free Cash Flow, r is the discount rate, and TV is the Terminal Value.
3. Why is the discount rate important in DCF Analysis?
The discount rate accounts for the time value of money and investment risk. A higher discount rate reduces the present value of future cash flows, while a lower discount rate increases the estimated intrinsic value. Selecting an appropriate discount rate is critical for accurate valuation.
4. What is Terminal Value in DCF Analysis?
Terminal Value (TV) represents the estimated value of a company beyond the explicit forecast period. Since businesses are expected to continue operating indefinitely, Terminal Value captures the present value of future cash flows after the forecast years and often represents a significant portion of the total DCF valuation.
5. What is the difference between Cash Flow (CF) and Free Cash Flow (FCF)?
Cash Flow (CF) is a general term that refers to the movement of cash into and out of a business. Free Cash Flow (FCF) is the cash remaining after a company has paid its operating expenses and capital expenditures. Because FCF reflects the cash available to investors, it is commonly used in DCF stock valuation.
6. What are the advantages of Discounted Cash Flow (DCF) Analysis?
DCF Analysis focuses on a company's future cash-generating ability rather than current market sentiment. It considers the time value of money, estimates intrinsic value, and supports long-term investment decisions based on business fundamentals.
7. What are the limitations of DCF Analysis?
The accuracy of DCF Analysis depends heavily on assumptions such as future cash flow projections, discount rate, and terminal growth rate. Small changes in these inputs can significantly affect the final valuation, making DCF sensitive to estimation errors.
8. Is DCF Analysis suitable for every company?
DCF Analysis works best for mature companies with stable and predictable cash flows. It may be less reliable for early-stage startups, highly cyclical businesses, or companies with uncertain future earnings because forecasting their cash flows is more difficult.
9. How do investors use DCF Analysis for stock valuation?
Investors calculate a company's intrinsic value using DCF Analysis and compare it with the current market price. If the intrinsic value is higher than the market price, the stock may be undervalued. If it is lower, the stock may be overvalued.
10. Which valuation method is better: DCF or P/E Ratio?
Both methods serve different purposes. DCF Analysis estimates a company's intrinsic value based on future cash flows, making it suitable for long-term valuation. The Price-to-Earnings (P/E) Ratio is useful for comparing similar companies within the same industry. Many professional investors use both methods together for a more comprehensive investment analysis.


