The Black Scholes Model estimates an option’s theoretical value using five important factors: the current price of the underlying asset, strike price, time to expiry, volatility and the risk-free interest rate.
For options traders, the Black Scholes Model can help explain why option premiums change and how factors such as volatility and time remaining until expiry influence the theoretical value of an option. However, the calculated value is a model-based estimate and should not be treated as a prediction of the future market price.
What Is the Black Scholes Model?
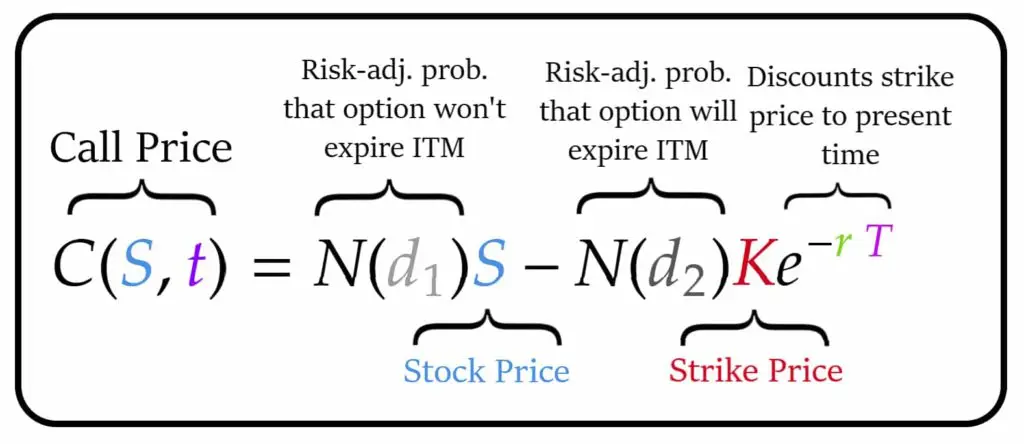
The Black Scholes Model in options trading provides a mathematical framework for calculating the theoretical price of an option based on a defined set of inputs.
The standard Black Scholes formula is primarily designed for European-style options, which can only be exercised on the expiration date. This differs from American-style options, which may be exercised before expiry.
The model is useful because it provides a consistent way to evaluate how different variables affect option prices rather than relying only on the premium currently quoted in the market.
A trader can use the calculated theoretical value as a reference point when analysing an option, but the actual market premium may be different because of liquidity, supply and demand, implied volatility, market events and other factors.
Key Inputs of the Black Scholes Model
The Black Scholes Model formula uses five major inputs to calculate the theoretical value of an option.
1. Current Price of the Underlying Asset (S)
This is the current market price of the stock or other underlying asset.
Changes in the underlying price directly affect the value of call and put options. Generally, a rise in the underlying price increases the value of a call option and decreases the value of a put option, assuming other factors remain unchanged.
2. Strike Price (K)
The strike price is the predetermined price at which the underlying asset can be bought or sold if the option is exercised.
The relationship between the current market price and strike price determines whether an option is in-the-money, at-the-money or out-of-the-money.
3. Time to Expiration (T)
Time to expiration represents the amount of time remaining until the option expires.
Options with more time remaining generally have greater time value because there is more opportunity for the underlying asset to move. As expiry approaches, the time value of an option generally decreases.
4. Volatility (σ)
Volatility represents the expected magnitude of price fluctuations in the underlying asset.
Higher volatility generally increases the theoretical value of both call and put options because a wider range of potential future prices increases the possibility that the option could become profitable before or at expiry.
Volatility is therefore one of the most important variables in an option pricing model.
5. Risk-Free Interest Rate (r)
The risk-free interest rate represents the theoretical return available from an investment with minimal default risk over a similar period.
Interest rates influence the present value of the strike price and therefore affect the theoretical values of call and put options.
Assumptions of the Black Scholes Model
The Black Scholes Model relies on several assumptions. Understanding these assumptions is important because real financial markets do not always behave exactly as the model expects.
The standard model assumes:
- The option is European-style and can only be exercised at expiry.
- The volatility of the underlying asset remains constant during the option’s life.
- The risk-free interest rate remains constant.
- Markets allow continuous trading.
- There are no transaction costs or taxes in the basic model.
- The underlying asset follows a continuous price process without sudden jumps.
- The original Black Scholes framework assumes that the underlying asset does not pay dividends during the option’s life.
Because actual markets can differ from these assumptions, the theoretical value calculated by the model may differ from the option’s traded market price.
Black Scholes Model Formula for Call and Put Options
The Black Scholes Model formula can be used to calculate the theoretical value of European call and put options.
Call Option Formula
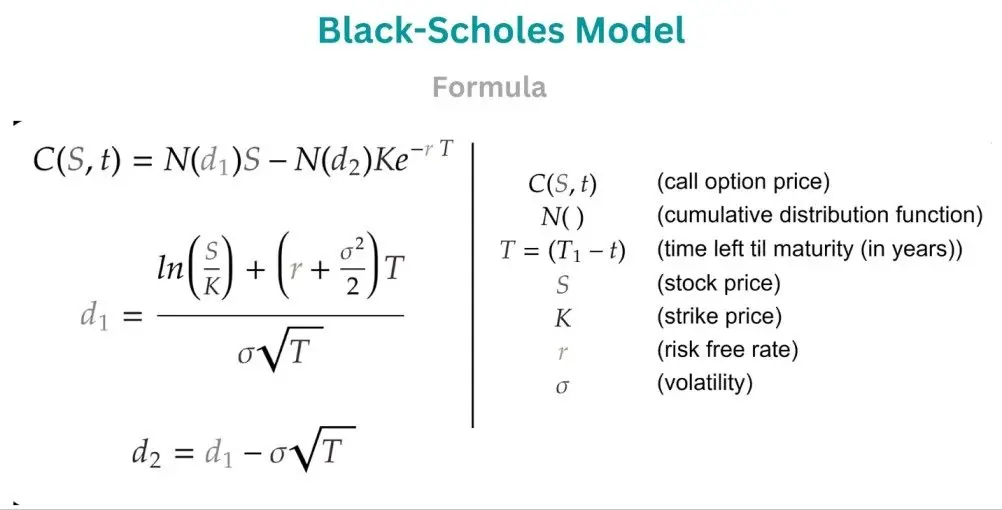
C = S₀N(d₁) - Ke^(-rT)N(d₂)
Where:
C = Theoretical value of the call option
S₀ = Current price of the underlying asset
K = Strike price
r = Risk-free interest rate
T = Time remaining until expiration
N(d) = Cumulative standard normal distribution
σ = Volatility of the underlying asset
The values of d₁ and d₂ are calculated as:
d₁ = [ln(S₀/K) + (r + σ²/2)T] / (σ√T)

d₂ = d₁ - σ√T
Put Option Formula
The theoretical value of a European put option can be calculated as:
P = Ke^(-rT)N(-d₂) - S₀N(-d₁)
Where P represents the theoretical value of the put option.
The formula combines the relationship between the underlying price, strike price, volatility, interest rate and remaining time to estimate the option’s theoretical value.
Black Scholes Model Example
Consider a hypothetical European call option with the following assumptions:
| Input | Value |
|---|---|
| Current Stock Price | ₹1,000 |
| Strike Price | ₹1,050 |
| Time to Expiry | 1 Year |
| Expected Volatility | 20% |
| Assumed Risk-Free Rate | 5% |
Using these values: d₁ ≈ 0.106 , d₂ ≈ -0.094
The corresponding cumulative normal distribution values are approximately:

N(d₁) ≈ 0.542 , N(d₂) ≈ 0.463
Using the call option formula: C = S₀N(d₁) - Ke^(-rT)N(d₂)
The theoretical call option value is approximately ₹80.
This value represents the model’s estimated theoretical price based on the assumptions provided. It does not mean that the option must trade at exactly ₹80 in the market. Actual option premiums can be higher or lower depending on market conditions, liquidity, implied volatility, supply and demand, upcoming events and other factors.
How Volatility Affects Black Scholes Option Pricing
Volatility has a significant influence on the theoretical value of options. When expected volatility increases, the potential range of future prices for the underlying asset becomes wider. This generally increases the theoretical value of both call and put options.
For example, suppose two options have the same:
- Underlying price
- Strike price
- Time to expiry
- Interest rate
If one option is based on an underlying asset with significantly higher expected volatility, that option will generally have a higher theoretical premium. This relationship is particularly important because option traders frequently evaluate implied volatility.
Implied volatility is the volatility level that, when entered into an option pricing model such as Black Scholes, produces a theoretical value close to the option’s current market price. It is therefore important to distinguish between historical volatility and implied volatility. Historical volatility measures past price movement, while implied volatility reflects the volatility implied by current option prices.
Why Theoretical Option Value Can Differ From Market Price
The Black Scholes Model calculates a theoretical value based on mathematical assumptions. The price available in the market is determined by actual trading activity.
Differences can occur because of:
- Changes in implied volatility
- Market supply and demand
- Bid-ask spreads
- Low or high liquidity
- Corporate announcements
- Earnings or financial results
- Economic events
- Interest rate expectations
- Dividend expectations
- Sudden price gaps
- Changes in market sentiment
For this reason, theoretical value should be considered a reference for option analysis rather than a guaranteed fair price or future trading price.
Black Scholes vs Other Option Pricing Models
Although the Black Scholes Model is widely used for understanding option valuation, other option pricing models can be more suitable in situations where Black Scholes assumptions do not apply.
| Pricing Method | Common Use | Key Strength | Main Limitation |
|---|---|---|---|
| Black Scholes Model | European-style options | Fast theoretical valuation | Relies on simplifying assumptions |
| Binomial Option Pricing Model | European and American-style options | Can incorporate early exercise | Requires more calculation steps |
| Monte Carlo Simulation | Complex or path-dependent options | Flexible for complex scenarios | Computationally intensive |
| Finite Difference Method | Complex option structures | Flexible numerical approach | More technical to implement |
Binomial Option Pricing Model
The Binomial Option Pricing Model divides the life of an option into multiple time periods and models possible upward and downward movements in the price of the underlying asset. A price tree is created, and the option value is calculated backward from expiration toward the present.
One important advantage of the binomial model is its ability to account for early exercise. This makes it useful when analysing American-style options.
Monte Carlo Simulation
Monte Carlo simulation estimates option values by generating a large number of possible future price paths for the underlying asset. The payoff from each simulated path is calculated, and these results are combined and discounted to estimate the option’s present theoretical value.
Monte Carlo methods can be useful for complex and path-dependent derivatives where a straightforward analytical formula may not be available.
Finite Difference Method
Finite difference methods use numerical techniques to solve the differential equations associated with option pricing. Instead of producing a value directly through a closed-form equation, the method divides price and time into a numerical grid and estimates option values across different scenarios.
These methods can be useful for more complex option structures but generally require greater computational resources and technical understanding.
Black Scholes Model vs Binomial Option Pricing Model
The Black Scholes Model and Binomial Option Pricing Model both estimate theoretical option values, but they use different approaches.
Black Scholes uses a continuous mathematical framework and provides a direct formula for European-style options.
The binomial model uses a step-by-step price tree in which the underlying asset can move up or down during each period.
| Feature | Black Scholes Model | Binomial Model |
|---|---|---|
| Calculation Method | Closed-form formula | Multi-step price tree |
| European Options | Yes | Yes |
| American Options | Standard model not designed for early exercise | Can incorporate early exercise |
| Calculation Speed | Generally faster | Depends on number of steps |
| Flexibility | Lower | Higher |
| Complexity | Relatively straightforward once inputs are available | Can become computationally intensive |
Neither model guarantees the actual future market price of an option. Their usefulness depends on the type of option being analysed and the assumptions used.
Advantages and Limitations of the Black Scholes Model
Advantages
- Standardized valuation framework : The model provides a consistent mathematical framework for estimating option values.
- Identifies major pricing variables : It clearly demonstrates how the underlying price, strike price, volatility, time and interest rates influence option valuation.
- Useful for comparison : Traders can compare theoretical values across different options using the same valuation framework.
- Foundation for advanced option analysis : Many concepts used in derivatives pricing and risk management build on principles associated with the Black Scholes framework.
Limitations
- Assumes constant volatility : Actual market volatility changes over time and can rise sharply around important events.
- Assumes constant interest rates : Interest rates can change during the life of an option.
- Standard formula focuses on European-style options : The standard Black Scholes formula does not directly account for the early exercise feature of American-style options.
- Market prices can move suddenly : Real markets can experience gaps and sharp movements that do not fit the model’s continuous-price assumptions.
- Transaction costs and market friction : Real trading includes brokerage costs, taxes, bid-ask spreads, liquidity constraints and other factors that are not included in the basic model.
Why the Black Scholes Model Matters in Options Trading
Understanding the Black Scholes Model in options trading can help traders understand the relationship between an option premium and its major pricing variables.
Instead of looking at an option premium as a standalone number, the model shows how its theoretical value is connected to:
- The underlying asset price
- Strike price
- Time remaining until expiry
- Expected volatility
- Interest rates
This can make it easier to understand why two options on the same underlying asset may trade at very different premiums.
The model is also closely connected with option risk measures known as the Greeks, including Delta, Gamma, Theta, Vega and Rho. These measures help describe how an option’s theoretical value may respond when different pricing variables change. The Black Scholes Model should therefore be viewed as an analytical framework rather than a trading signal or prediction of future returns.
Key Takeaways
- The Black Scholes Model is one of the best-known mathematical frameworks for estimating the theoretical value of European-style options.
- It uses five major inputs: underlying asset price, strike price, time to expiry, volatility and the risk-free interest rate.
- Volatility is particularly important because changes in expected volatility can significantly affect option premiums.
- The model has limitations because real markets do not always follow assumptions such as constant volatility, constant interest rates and continuous price movements.
- Alternative methods such as the Binomial Option Pricing Model, Monte Carlo simulation and finite difference methods can be useful when more flexibility or different option characteristics need to be considered.
- Theoretical option value should be used as an analytical reference rather than as a guarantee of the price at which an option will trade.
Frequently Asked Questions About the Black Scholes Model
What is the Black Scholes Model?
The Black Scholes Model is a mathematical option pricing model used to estimate the theoretical value of European-style call and put options using variables such as the underlying price, strike price, time to expiry, volatility and risk-free interest rate.
What are the five main inputs in the Black Scholes Model?
The five primary inputs are the current price of the underlying asset, strike price, time to expiration, volatility and risk-free interest rate.
What is the Black Scholes Model formula used for?
The Black Scholes Model formula is used to estimate the theoretical value of European call and put options based on specified market and option variables.
Can the Black Scholes Model be used for American options?
The standard Black Scholes formula is designed for European-style options and does not directly incorporate early exercise. Models such as the binomial option pricing model can incorporate the possibility of early exercise.
How does volatility affect the Black Scholes Model?
Higher volatility generally increases the theoretical value of both call and put options, assuming other inputs remain unchanged, because greater volatility increases the range of possible future prices.
What is implied volatility in the Black Scholes Model?
Implied volatility is the volatility level that makes an option pricing model produce a theoretical value consistent with the option’s observed market price. It reflects the volatility implied by current option pricing.
Why is the Black Scholes price different from the market option price?
Actual option prices are affected by supply and demand, liquidity, bid-ask spreads, implied volatility, market events and other factors. The Black Scholes value is a theoretical estimate based on specific assumptions.
What is the difference between the Black Scholes and Binomial models?
Black Scholes uses a continuous mathematical framework and a closed-form formula, while the binomial model divides time into multiple steps and creates a price tree. The binomial approach can also incorporate early exercise.
Does the Black Scholes Model predict future option prices?
No. The Black Scholes Model estimates theoretical option value using specified inputs and assumptions. It does not predict the future market price or profitability of an option trade.
Related tools and guides
For live data and further reading, see the option greeks calculator, implied volatility and option greeks and option greeks explained.